Phone
Consular Issues
Phone
Uzbekistan news
We recommend
Through the Caspian to New Markets
📅 21.07.2026
Development of the “Central Asia Plus” Formats
In recent years, Central Asia has increasingly acted as a unified region in international relations. Alongside bilateral ties, “Central Asia Plus” formats have been developing, allowing the countries to coordinate their shared interests and discuss trade, investment, industrial cooperation, transportation, energy, and security with external partners.
Existing formats include “Central Asia–European Union,” “Central Asia–Russia,” the C5+1 platform with the United States, as well as dialogue mechanisms with China, Japan, South Korea, and other partners. These mechanisms do not replace bilateral cooperation but complement it with a regional agenda.
Central Asia’s Multivector Cooperation
The first “Central Asia–European Union” summit, held in Samarkand in April 2025, focused on developing a strategic partnership between the two regions. Particular attention was paid to investment, technological modernization, green energy, critical minerals, transportation, and logistics.
Uzbekistan proposed establishing an investment platform to advance regional projects and developing coordinated conditions for expanding the Trans-Caspian Transport Corridor. It also proposed holding a meeting of the transport ministers of the countries located along the route.
The second “Central Asia–Russia” summit, held in October 2025, focused on expanding trade, industrial cooperation, and collaboration in energy and transportation.
Uzbekistan proposed holding annual summits, establishing a coordination council at the deputy prime minister level, and creating an integrated transportation and logistics framework combining national road, rail, and air connectivity programs. Particular attention was also paid to developing the North–South Corridor and resilient production chains.
Thus, the “Central Asia Plus” formats enable the region to develop cooperation in several areas simultaneously. Their purpose is not to choose a single partner or route, but to expand economic ties and strengthen the region’s resilience to external changes.
Establishing a New C5+1 Format
The “Central Asia + Azerbaijan” format differs from other platforms because Azerbaijan is directly connected to the region through the Caspian Sea and is a key component of transportation routes leading toward the South Caucasus, Türkiye, and Europe.
For Central Asia, Azerbaijan is an important transit, investment, and industrial partner. For Azerbaijan, the Central Asian countries represent a growing market and a source of cargo flows for its port, railway, and logistics infrastructure. The new format therefore has not only political significance but also a specific economic dimension.
At the seventh Consultative Meeting of the Heads of State of Central Asia, held in Tashkent on November 16, 2025, a decision was made to grant Azerbaijan full participation. This became the first meeting of regional leaders in the expanded format.
President of Uzbekistan Shavkat Mirziyoyev proposed gradually transforming the consultative dialogue into a strategic “Central Asian Community” format. Initial steps included strengthening the institutional framework of the meetings, establishing a rotating secretariat, and elevating the status of national coordinators to special representatives of the presidents.
In trade and economic cooperation, Uzbekistan proposed developing a Comprehensive Regional Program for Trade and Economic Cooperation through 2035. The document is expected to address the removal of administrative barriers, simplification of customs and tax procedures, joint use of industrial and free economic zones, and other measures to increase intraregional trade.
Initiatives were also proposed to establish a common investment space and develop e-commerce. These measures include coordinating basic approaches to investor protection, creating regional digital marketplaces, and developing reliable digital payment systems.
Particular attention was paid to transportation and energy infrastructure. Uzbekistan proposed establishing an Infrastructure Development Council at the deputy prime minister level. Priorities included the construction and modernization of roads, railways, border checkpoints, energy networks, green corridors, and digital infrastructure.
Transportation initiatives covered the China–Kyrgyzstan–Uzbekistan railway, the Trans-Afghan route, and the Trans-Caspian transportation routes connecting Central Asia with the markets of the Caucasus, Türkiye, and Europe.
In 2026, the meeting is expected to continue under Turkmenistan’s chairmanship in the new “Central Asia and Azerbaijan” format.
Economic Foundation of Cooperation
The expansion of the regional format is taking place against the backdrop of growing trade and investment ties between Uzbekistan and the Central Asian countries.
In 2025, Uzbekistan’s trade turnover with the countries of the region reached $8.3 billion. Exports totaled approximately $3.2 billion, while imports amounted to $5.1 billion. Kazakhstan remained Uzbekistan’s largest regional trading partner, accounting for 60.2% of its trade with Central Asian countries. Turkmenistan and Kyrgyzstan each accounted for 14.5%, while Tajikistan accounted for 11%.
As of June 2026, Uzbekistan was home to 2,384 enterprises with capital from Central Asian countries. These included 1,283 enterprises with Kazakh capital, 442 with Tajik capital, 362 with Kyrgyz capital, and 297 with Turkmen capital.
The total volume of direct investment and loans attracted from the countries of the region in 2017–2025 amounted to $2.5 billion. In 2025 alone, this figure reached $1.3 billion.
At the same time, the potential of intraregional trade has not been fully utilized. According to calculations by the Center for Economic Research and Reforms, replacing some goods imported from third countries with intraregional supplies could increase trade within Central Asia by $11.4 billion, more than doubling its current volume. Unlocking this potential requires reducing tariff and non-tariff barriers, improving information exchange among businesses, and developing regional production chains.
Uzbekistan’s economic relations with Azerbaijan are also strengthening. Between 2017 and 2025, bilateral trade increased 9.5-fold, from $32.5 million to $307.3 million. Uzbekistan’s exports reached $227.3 million, while imports from Azerbaijan amounted to $80 million.
Uzbekistan’s exports mainly consist of manufactured goods, machinery and transportation equipment, food products, beverages, finished goods, and services. Imports are dominated by food and manufactured goods, machinery, transportation equipment, and chemical products.
Uzbekistan is home to 460 enterprises with Azerbaijani capital. Their number has increased 6.5-fold since 2017. In 2025, Azerbaijani investment in Uzbekistan totaled $173.7 million, bringing cumulative investment to $318.6 million.
An additional instrument was created in 2023 with the establishment of the Azerbaijan–Uzbekistan Investment Company, which has authorized capital of $500 million and can finance projects in Uzbekistan, Azerbaijan, and third countries.
Cooperation is also developing in the automotive industry, textiles, construction, agriculture, and other sectors.
The Middle Corridor and Azerbaijan
Expanding trade and industrial cooperation requires reliable transportation infrastructure. For Uzbekistan, which has no direct access to the sea, developing alternative routes is essential to strengthening the resilience of foreign trade.
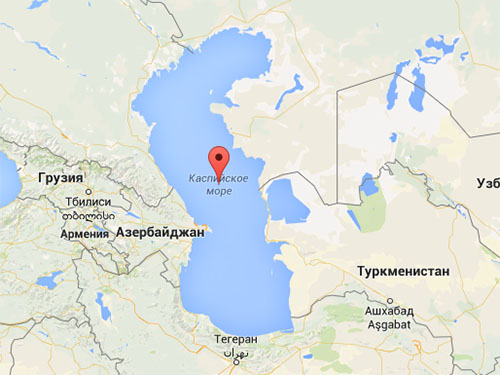
The Middle Corridor connects China and Central Asia with the South Caucasus, Türkiye, and Europe. Cargo from Uzbekistan can be transported through Kazakhstan or Turkmenistan to Caspian ports, shipped by sea to Azerbaijan, and then delivered to European markets through Georgia and Türkiye or across the Black Sea.
Azerbaijan occupies a central position in the western section of the route. Its transportation infrastructure includes the Alat International Sea Trade Port, the Caspian merchant fleet, and the Baku–Tbilisi–Kars railway.
The capacity of the Alat Port is expected to increase from 15 million to 25 million metric tons, while the capacity of the Baku–Tbilisi–Kars railway has been expanded to 5 million metric tons. A unified digital platform is also being developed to simplify transportation operations and trade between Caspian ports.
According to the World Bank, if the necessary infrastructure and organizational reforms are implemented, freight traffic along the Middle Corridor could triple by 2030, while delivery times could be reduced by half.
During the first nine months of 2025, transit freight between Uzbekistan and Azerbaijan exceeded 1 million metric tons. This indicates growing prospects for using Azerbaijan’s transportation infrastructure as a transit route for Uzbek cargo.
The opening of the Zangezur Corridor is also expected to create additional opportunities for all Central Asian countries.
Opportunities for Uzbekistan and Central Asia
For Uzbekistan, the Middle Corridor provides an additional route to the markets of Azerbaijan, Georgia, Türkiye, and the European Union. This makes it possible to diversify transportation routes and reduce foreign trade dependence on a limited number of corridors.
Delivery times and predictability are especially important. They directly affect the competitiveness of textiles, fruits and vegetables, electrical equipment, automobiles, and other high-value-added products. Coordinating rail and maritime transportation schedules, introducing digital documentation, and reducing border-crossing times could lower exporters’ costs.
The corridor’s development will also create demand for dry ports, multimodal terminals, warehouses and cold-storage facilities, repair enterprises, and insurance, financial, and digital services. Transportation can therefore be viewed not only as a means of delivering goods but also as a separate area of investment and industrial development.
Additional opportunities are associated with the construction of the China–Kyrgyzstan–Uzbekistan railway. Its integration with the Middle Corridor would establish a shorter and more resilient transportation link between China, Central Asia, the Caucasus, and Europe.
For Central Asia as a whole, developing the route would make it possible to consolidate cargo flows, harmonize transportation procedures, and increase the region’s attractiveness to international investors. A larger and more stable cargo base would support regular train and vessel services, reduce per-unit costs, and expand the geographic reach of shipments.
The Middle Corridor is not viewed as a replacement for northern or southern routes. Its main purpose is to expand available options, strengthen logistics resilience, and create additional connections to external markets.
The Importance of Industrial Cooperation
Transportation cooperation will have a long-term impact if it is linked to the development of manufacturing. Growth in transit alone will not ensure the full realization of the new format’s economic potential.
Uzbekistan, other Central Asian countries, and Azerbaijan could establish joint production chains in the automotive industry, textiles, agricultural processing, electrical engineering, construction materials, chemicals, and machinery manufacturing.
An analysis by the Center for Economic Research and Reforms shows that regional enterprises could supply one another with raw materials, components, and finished products, reducing their dependence on imports from third countries.
One promising area is the establishment of joint industrial zones and logistics centers along the Middle Corridor. The idea of creating “mirror” special economic zones in Uzbekistan and Azerbaijan has not yet reached the implementation stage, but it offers significant development potential.
At the same time, growing bilateral trade, the work of the joint investment company, and expanding transportation links are creating conditions for revisiting this initiative.
Such zones could specialize in product assembly and processing, consolidation of export shipments, warehousing operations, and transportation services. Establishing interconnected production facilities in Uzbekistan and Azerbaijan would combine Central Asia’s industrial potential with the transportation infrastructure of the South Caucasus.
Conclusion
The first meeting in the expanded format established a political and institutional foundation for cooperation between Central Asia and Azerbaijan. The next meeting, under Turkmenistan’s chairmanship, could focus on the practical development of the Middle Corridor and the expansion of industrial cooperation.
In transportation, the main priorities include coordinating tariffs and procedures, developing regular rail and maritime services, modernizing port and border infrastructure, digitizing documentation, and exploring opportunities to connect the Middle Corridor with the China–Kyrgyzstan–Uzbekistan railway.
In industry, priorities could include establishing joint production chains, developing industrial zones, implementing projects through the Azerbaijan–Uzbekistan Investment Company, and attracting international financial institutions to infrastructure and manufacturing projects.
For Uzbekistan, the “Central Asia + Azerbaijan” format creates opportunities to expand exports, diversify transportation routes, and attract investment in manufacturing and logistics. For other Central Asian countries, it provides an additional route to Western markets.
The format’s future significance will depend on how consistently the participating countries develop the Middle Corridor and complement the transportation agenda with industrial and investment cooperation. The upcoming meeting could provide practical momentum for implementing the most ambitious and mutually beneficial projects.
Edvard Romanov,
Center for Economic Research and Reforms
Business Climate Analysis of Uzbekistan – CERR Survey
📅 27.02.2026
In January, growth in the business climate was mainly driven by an outpacing increase in the expectations component. The agricultural sector and services became the key drivers of business confidence.
The Center for Economic Research and Reforms (CERR) presented the results of its business climate analysis based on monthly surveys of entrepreneurs across the republic. Based on the collected data, a composite Business Climate Indicator was formed, reflecting both current assessments of business conditions and expectations for the next 3 months.
Dynamics of Uzbekistan’s Composite Business Climate
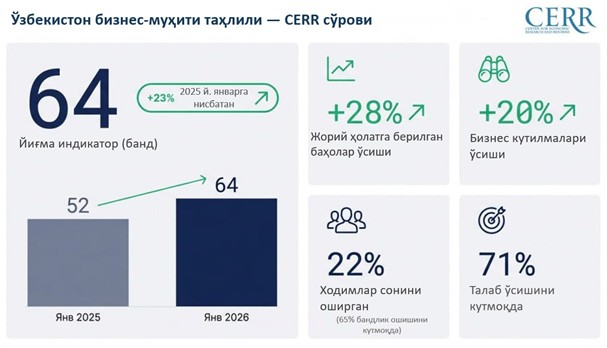
In January of the current year, Uzbekistan’s composite Business Climate Index stood at 64 points (on a scale from −100 to +100), which is 23% higher than the level of 2025.
The improvement in the business climate was primarily driven by stronger assessments of the current business situation, which increased by 28%.
An additional contribution came from improved optimism regarding short-term business prospects. In particular, business expectations rose by 20%.
According to the survey, 22% of enterprises increased their number of employees. At the same time, 71% of respondents expect demand for their products to grow over the next three months, compared to about 60% in the same period last year.
The share of enterprises forecasting an increase in employment in the coming quarter rose to 65%, up from 58% a year earlier.
Sectoral Dynamics of the Business Climate Index
In sectoral terms, an improvement in the business climate compared to last year was observed in construction, agriculture, and services.
In agriculture, the Business Climate Index increased by 62% year-on-year and reached 77 points, compared to 48 points in January 2025.
Growth was mainly supported by a significant improvement in assessments of current conditions and more favorable expectations. The current situation indicator in the sector increased 2.7 times from 27 to 72 points, while expectations grew by 17% to reach 82 points.
44% of entrepreneurs assessed the condition of their business in the sector as “good,” compared to 39% a year earlier. Growth in demand for products over the past three months was reported by 46% of enterprises versus 39% in January last year. Expectations for further demand growth in the near term remain high at 71%, compared to 68% a year earlier.
In the services sector, the business climate increased by 25% compared to January last year, reaching 65 points versus 52 points a year earlier.
Growth was driven by a gradual improvement in current business conditions. Current assessments in services rose by 18% to 52 points. At the same time, a more pronounced increase was observed in the expectations component, which grew by 32% to 79 points, indicating a substantial strengthening of companies’ confidence in short-term prospects.
70% of entrepreneurs expect demand for their services to grow over the next three months, compared to 58% in January 2025. The share of enterprises expecting to increase employment in the coming quarter amounted to 61%, up from 54% a year earlier.
In the construction sector, the business climate increased by 13% to 61 points, compared to 54 points a year earlier. The current situation indicator improved by 43% to 57 points. Expectations were formed at the level of 66 points, showing a decline of 4%.
38% of respondents reported that business conditions in construction had improved over the past three months, compared to 35% a year earlier. The share of enterprises reporting workforce growth rose to 38% from 22% a year earlier. Expectations of demand growth over the next three months were expressed by 77% of entrepreneurs, compared to 61% in January last year.
In industry, the business climate slightly declined by 5% compared to last year, while remaining at a sufficiently high level of 54 points.
At the same time, optimism among industrial enterprises remains steadily high. In January, expectations increased by 10%, reaching 78 points, indicating a continued positive outlook regarding development prospects.
According to the survey, the share of respondents reporting an improvement in business conditions over the past three months reached 32%, compared to 30% a year earlier. Demand growth over the same period was noted by 38% of industrial enterprises versus 36% in January last year. Meanwhile, employment expansion plans strengthened — 69% of entrepreneurs expect to increase their workforce in the next three months, compared to 62% a year earlier.
Barriers to Entrepreneurial Activity
According to the survey, more than half (57%) of entrepreneurs see no barriers in their activities. Among the problems cited, the most frequent are taxation (11%), utilities (9%), and access to credit (8%).
CERR Sector for the Study of Sectoral Competitiveness and Investment Activity
Tel: (78) 150 02 02 (441)
CERR Public Relations and Media Sector
Tel: (78) 150 02 02 (417)
Tashkent to Host Second Meeting of Termez Dialogue on Connectivity Between Central and South Asia on June 4–6
📅 31.05.2026
On 4-6 June, Tashkent will host the second meeting of the Termez Dialogue on Connectivity between Central and South Asia under the theme: “Peace, Connectivity, and Resilience: Shaping the Foundation for Shared Prosperity”.
Established in 2025 as a permanent international platform, the Termez Dialogue is intended to facilitate the practical advancement of the initiative put forward by the President of Uzbekistan, Shavkat Mirziyoyev, aimed at strengthening interconnectivity between Central and South Asia. This initiative has received broad international support and was enshrined in a special resolution adopted by the United Nations General Assembly on 11 July 2022.
The current meeting is organized by the Institute for Strategic and Regional Studies under the Head of our State and the Ministry of Foreign Affairs of Uzbekistan in partnership with the Conference on Interaction and Confidence Building Measures in Asia (CICA).
The forum will bring together more than 150 representatives of political, business, and expert communities, as well as international and regional organizations from Central and South Asia, Europe, the CIS, the South Caucasus, the Asia-Pacific region, the Middle East, and the Americas. This underscores the inclusive and open nature of the Termez Dialogue as a comprehensive international platform for developing joint approaches to strengthening connectivity, trust, and sustainable development across the Eurasian space.
Partners and participants of the Dialogue include the United Nations Regional Centre for Preventive Diplomacy for Central Asia (UNRCCA), the United Nations Assistance Mission in Afghanistan (UNAMA), as well as leading think tanks, research institutions, and peacebuilding organizations, including the International Water Management Institute (IWMI), the Center for Progressive Reforms, the Konrad Adenauer Foundation, the Berghof Foundation, PeaceNexus, Search for Common Ground, Georgetown University, and other organizations.
The forum programme includes a high-level plenary session on the theme: “Political Dialogue and Economic Connectivity as Pillars of Sustainable Development in the CICA Region”, as well as two special thematic sessions dedicated to joint climate change adaptation and environmental sustainability, and to deepening cultural and humanitarian cooperation.
The event will also feature expert and academic discussions, as well as side events devoted to regional security, expanding engagement with Afghanistan, including the development of the Afghanistan–Uzbekistan–Pakistan dialogue, strengthening transport and logistics connectivity, fostering regional trust, and advancing a common sustainable development agenda. Particular attention will be paid to issues of Central Asian regional identity, as well as to expanding youth cooperation in the fields of peacebuilding and sustainable development.
The forum programme also envisages off-site sessions. Participants of the Dialogue are scheduled to visit Termez, where they will have an opportunity to familiarize themselves with the modern trade, economic, and logistics infrastructure supporting cooperation with South Asian countries, including the operations of the Airitom International Trade Center and the international logistics hub Termez Cargo Center, as well as experience the rich cultural and historical heritage of the ancient city.
The third day of the Dialogue will take place in Samarkand, where delegates will explore the unique civilizational heritage of the Samarkand Renaissance, which historically served as a bridge between East and West, North and South.
The meeting is expected to conclude with the adoption of a Communiqué intended to reaffirm the commitment to strengthening trust, advancing constructive cooperation, and promoting sustainable connectivity between Central and South Asia.
Dunyo IA

Writers’ Union of Uzbekistan
📅 03.06.2025
Academy of Sciences of the Republic of Uzbekistan
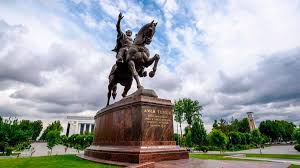
A masterpiece of our distinguished history
📅 18.03.2026
During one of his visits to the Kashkadarya province, President of Uzbekistan, Shavkat Mirziyoyev, emphasized the profound wisdom and exemplary value embedded in the literary works dedicated to our historical figures. In particular, he highlighted the significance of texts related to Amir Temur, most notably the Temur tuzuklari (Institutes of Temour), which he identified as a critical source for understanding our national heritage. The President stressed again the necessity of comprehensive scholarly engagement with this text, recognizing it as a testament to the intellectual and statecraft traditions of the Uzbek people.
The Temur tuzuklari commissioned by Amir Temur, occupies a prominent place in the historiography of world civilization. Its significance is multifaceted. First, the authorship is attributed to a statesman of exceptional strategic and intellectual capacity, and the text has remained a subject of sustained scholarly interest. Second, the clarity of the work’s prose enhances both its accessibility and its continued relevance. Third, the work was produced in a period marked by geopolitical realignments and intellectual developments that would later contribute to the European Renaissance. Finally, Amir Temur’s enduring stature within a multipolar global order, all of these factors emphasize the broader historical value of the text, which continues to engage both academic and general audiences.
Temur tuzuklari is a very simple yet deeply meaningful and richly substantive work. To write such a piece, the author must possess a broad worldview, have personally experienced the heavy footsteps of history and the hardships of building an immense state, and must have attained the status of a noble figure who could easily fathom the world, deeply understand history and geography, be well-versed in ethnonymy, toponymy, and be capable of drawing profound conclusions about life, the flow of the world, and the paths of existence, a figure at the level of a wise philosopher. In other words, the Turon saltanati (Turanian kingdom) was the creation of Amir Temur. He referred to himself as the “Sultan of Turan”. In 1391, these words were inscribed in Old Uzbek on stone in Dasht-i Kipchak Steppe. That empire was built through the arduous labor of our forefather, and its institutions did not emerge spontaneously, but arose from pressing necessity (emphasis by the author). Temur tuzuklari came about as a vivid expression of all of this.
Only an individual of Amir Temur’s stature, who, as the historian Nizomiddin Shomiy described, attained perfection and high rank through his own mature effort and determined striving,” and who had acquired firsthand experience in the art of empire-building, could have created the Tuzuklar. The authorship of such a piece lies solely within the capacity of such a figure; there can be no room for doubt in this regard. In fact, a close reading of the Temur tuzuklari reveals the expansive intellectual breadth of its author.
Another important point: it would be illogical, a fundamental error, to suggest that this intellectually rich and thematically mature work, which has been the subject of scholarly inquiry for six centuries and continues to attract global interest, was authored by an anonymous writer and merely “presented” to Amir Temur, with authorship later attributed to him as a gesture of “flattery”. Such speculation lacks credibility. Moreover, Major William Davy, Persian secretary to the Commander in Chief of the Bengal Forces, was the first translator of the Tuzuklar into English, emphasizing that Amir Temur was the genuine author of the work.
The composition of the Tuzuklar appears to have been an iterative process, spanning several years and undergoing multiple revisions, abridgments and expansions.
The Arab historian Mazhar Shihab, as cited by Ubaydulla Uvatov, affirms that “Amir Temur began recording his memoirs long before he assumed power”. This observation suggests that Temur maintained a long-standing interest in documenting his thoughts and experiences and that he may have been reluctant to delegate such a task to others, either out of concern for accuracy or due to the absence of individuals he deemed suitably qualified.
The Temur tuzuklari, enriched with wisdom, also offers invaluable insight into Amir Temur’s character. The text depicts him as a champion of justice, committed to truth, loyalty, and the well-being of his people. He is portrayed as magnanimous, fearless, and principled ruler. He bravely strives to uphold the rights of the oppressed against the tyrants, for he knows that a country may endure with disbelief but cannot tolerate oppression.
Alisher Navoi, a contemporary of Amir Temur’s legacy, begins the seventh chapter (majlis) of his work “Majalis un-Nafais” (The Assemblies of the Refined) with the name of Amir Temur Kuragon. Navoi portrays the Sahibkiran as an intellectual and a man of high spirituality, awarding him the most prestigious place among the “refined souls”.
Navoiy also recounts a remarkable episode that illustrates the Sohibqiron’s powerful memory. When a long-sought criminal–Xoja Abdulkadir Marogi, famous composer, musician, the Qur’an reciter–was finally brought before Amir Temur, the man began reciting the Qur’an in a melodious voice. Moved by the recitation, Temur’s wrath softened and he forgave the offender. Deeply affected, the Sohibqiron then recited a line of poetry in response.
Navoiy was astonished by this poetic line. The Sohibqiron had recited the fourth line of a rubai (quatrain) composed by the renowned Sufi poet and sheikh Abusaid Abulxayr, who had lived about four centuries earlier. Amir Temur had become enamored with this verse and had committed it to memory. This incident reveals not only his deep appreciation for poetry but also his exceptional memory and reverence for spiritual literature. These are precisely such moments that justify the inclusion of Temur’s name in “Majalis un-Nafais”.
Amir Temur was deeply invested in ensuring the accuracy and truthfulness of the work being produced. In this context, the guidance, instructions, demands, advice, and reflections he directed toward the authors, reflecting his intellectual acuity and refined cultural sensibilities, are particularly compelling and merit close scholarly attention.
One thing appears particularly striking: for nearly two centuries after Amir Temur’s death, no information can be found regarding Tuzuklar or its fate. The work seemed to have been engulfed in a darkness of neglect and oblivion.
“The 'Tuzuk-i-Timuri” (Temur Tuzuklari) was a high document of the empire and a state secret; such a document exists in only one, at most two copies, kept in strict confidentiality and secrecy.
Major Davy once wrote the following about Boburnoma: “The book of Baburnama, too, remained in the shadows of neglect and forgetfulness until nearly the middle of the reign of Bobur’s grandson, Emperor Akbar (1566–1605), when it was finally translated from Chagatai Turkic into Persian. Until that time, no one in either Asia or Europe had questioned the authenticity of Babur’s memoirs. Nevertheless, this work, like Tuzuklar, eventually faced a similar degree of scholarly neglect.
An essential scholarly and cultural imperative now rests with leading institutions, including the International Amir Temur Public Foundation, the State Museum of the History of the Temurids, the Al-Beruniy Institute of Oriental Studies of the Academy of Sciences of Uzbekistan, Institute of History of the Academy of Sciences and the Center for Islamic Civilization in Uzbekistan, as well as with the broader intellectual community: namely, to locate the original manuscript of the “The 'Tuzuk-i-Timuri” - Temur tuzuklari, subject it to rigorous academic scrutiny, and reintegrate this foundational text into the corpus of the nation’s cultural and historical legacy.
The recovery of the authentic manuscript, an unparalleled artifact that reflects the political thought and historical consciousness of a pivotal epoch, would constitute a landmark achievement in the advancement of Uzbek historiography and civilizational self-understanding.
Muhammad ALI
Chairman, International Amir Temur Public Foundation
Distinguished Writer of Uzbekistan, Professor
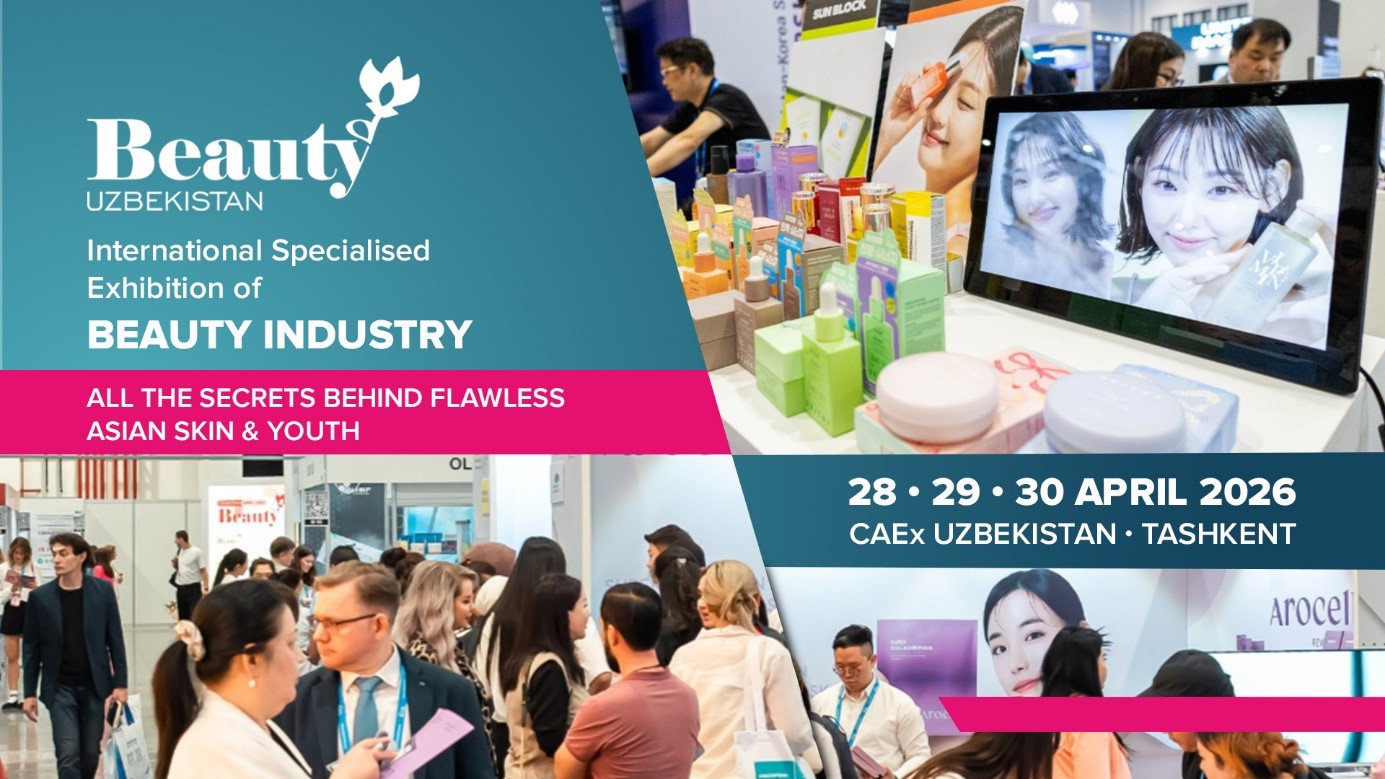
Beauty Uzbekistan 2026 International Exhibition to Be Held in Tashkent on April 28–30
📅 24.04.2026
The exhibition will bring together more than 100 companies and brands from 12 countries.
The specialised international exhibition of the beauty, cosmetology, and perfumery-cosmetics industry – Beauty Uzbekistan 2026 – will take place from April 28 to April 30 at the CAEx Uzbekistan exhibition complex in Tashkent.
Beauty Uzbekistan is a professional B2B exhibition that brings together manufacturers and distributors of cosmetic products, aesthetic medicine specialists, retail representatives, salon business owners, and professionals in the personal care sector. The exhibition provides direct access to leading global brands, innovative products, and cutting-edge technologies, while offering valuable opportunities to establish business connections, and gain early insight into key trends in the beauty industry.
The exhibition will feature more than 100 companies and brands from 12 countries: Azerbaijan, China, Georgia, Italy, Kyrgyzstan, Republic of Korea, Poland, Russia, Sweden, Spain, UAE, and Uzbekistan. National pavilions from the Republic of Korea and Poland will showcase advanced beauty industry solutions and the export potential of these countries.
According to the organizers, the main sections of the exhibition are:
- Beauty Uzbekistan – covering the full spectrum of the perfumery and cosmetics industry, including makeup and skincare cosmetics, fragrances, personal care products, and hair industry products.
- Beauty Derma Central Asia – a dedicated segment focused on aesthetic medicine, device-based cosmetology, and anti-ageing solutions. This section of the exhibition will present advanced technologies for clinics and industry professionals, including injectable treatments, as well as next-generation laser and energy-based technologies.
Traditionally, the exhibition will feature a comprehensive business programme, including specialised seminars, expert-led sessions, and professional discussions.
Dedicated programme segments will address key developments in aesthetic medicine, balneology, and SPA industry, including scientific approaches in aesthetic medicine (CYTOLIFE / MedTenderGroup, Russia), as well as advanced solutions in balneological equipment and hydrotherapy technologies (Physiotechnika, Russia).
A specialised session on fragrance solutions presented by the Swiss Company LUZI may be of particular interest to industry professional and household chemical manufacturers.
Beauty Uzbekistan 2026 is more than just an exhibition — it is a dynamic professional platform where business, medicine, technology, and the latest beauty trends converge.
The event is organised by Iteca Exhibitions, an international exhibition company, in partnership with ICA Eurasia Group, informed that one can register to visit the exhibition on the website: www.beautypro.uz.
IA “Dunyo”
Uzbekistan and Belgium: Toward a New Stage of Strategic Partnership with the European Union
📅 29.10.2025
In October, the President of the Republic of Uzbekistan, Shavkat Mirziyoyev, will pay a state visit to the Kingdom of Belgium, during which important decisions are expected to be made that will mark a qualitatively new stage in relations between Uzbekistan and the European Union. In particular, the visit will feature the signing of the Agreement on Enhanced Partnership and Cooperation.
In recent years, Uzbekistan has been actively shaping a new framework of engagement with Europe – a key pillar of stability amid current geopolitical tensions and global economic uncertainty. The ties between Uzbekistan and European countries continue to grow, and the areas of cooperation are diversifying, supported by the ongoing reforms in Uzbekistan.
Building a New Chapter in Relations
After gaining independence, Uzbekistan’s relations with the European Union developed dynamically. A Memorandum of Understanding between the Government of Uzbekistan and the European Commission was signed in 1992, followed by the establishment of diplomatic relations in 1994. The foundation of cooperation was laid by the Partnership and Cooperation Agreement (PCA) signed in June 1996 and entering into force in 1999. However, at a certain stage, cooperation faced difficulties due to the insufficient pace of democratic reforms in Uzbekistan.
With the election of Shavkat Mirziyoyev as President, the situation changed dramatically. As early as 2017, during his visit to Tashkent, Stefano Manservisi, Director-General for International Cooperation and Development of the European Commission, stated that “the EU regards Uzbekistan as a strategic partner.” The sweeping democratic and economic reforms launched in Uzbekistan helped resolve within a short period many issues that had long remained unsolved. Forced labor was completely eradicated, and reforms in the cotton sector enabled the country to abandon raw cotton exports altogether.
As reforms advanced, the legal and institutional framework of relations with Europe expanded rapidly. While previously Uzbekistan and the EU granted each other most-favored-nation treatment under the PCA, in April 2021 the EU granted Uzbekistan GSP+ beneficiary status, and in 2022 the Enhanced Partnership and Cooperation Agreement (EPCA) was initialed.
Along with internal transformation, Uzbekistan’s foreign policy architecture also changed. Priority was given to closer cooperation with neighboring Central Asian states, as well as the active expansion of ties with European countries – a vector that has strengthened steadily in recent years.
Just in the past year, Uzbekistan established strategic partnership relations with France, Italy, and Slovakia, while discussions on expanding strategic cooperation with Hungary continued. President Mirziyoyev also visited Slovenia, and Italy’s Prime Minister and Bulgaria’s President visited Uzbekistan.
A milestone in strengthening relations between Uzbekistan and Europe, and between Europe and Central Asia as a whole – was the first EU–Central Asia Summit, held in Samarkand in April 2025 under the chairmanship of Shavkat Mirziyoyev. Uzbekistan presented a broad range of initiatives to create a new model of regional cooperation between Central Asia and Europe, including: a multilateral agreement on investment protection and promotion; the launch of a Central Asia–EU Joint Chamber of Commerce; the adoption of a regional support program for SMEs and women’s entrepreneurship; the establishment of an investment platform to promote regional projects in green energy, innovation, transport, infrastructure, and agriculture.
The Samarkand Summit was highly productive. A Joint Declaration was adopted, establishing a strategic partnership between the two regions in trade, transport, energy, digital connectivity, and water management. European Commission President Ursula von der Leyen announced that the EU had prepared a €12 billion investment package for Central Asia under the Global Gateway initiative.
The Trajectory of Economic Cooperation
Uzbekistan’s deep democratic transformations have significantly improved relations with European countries. Economic reforms have enhanced the competitiveness of Uzbekistan’s economy, stimulating investor confidence and growing interest from European businesses.
The results are impressive. Over the past 8 years, Uzbekistan’s GDP has doubled, reaching $115 billion in 2024. Since 2017, investment in fixed capital has totaled $240 billion, of which foreign investment exceeded $130 billion. The country’s foreign exchange reserves surpassed $48 billion for the first time in history. Structurally, the share of industry in the economy increased from 20% to 26%, and services from 44% to 47%. Labor productivity (GDP per employed person) rose by 45%.
As a result, opportunities for mutually beneficial cooperation between Uzbek and European businesses have expanded. Between 2017 and 2024, Uzbekistan’s trade with the EU increased 2.4 times to $6.4 billion; exports grew 3.6 times to $1.7 billion, and imports 2.2 times to $4.7 billion. In 2024, the EU’s share in Uzbekistan’s total trade turnover was 9.7%, in exports 6.3%, and in imports 12%. The EU ranked third among Uzbekistan’s trade partners, after China and Russia.
The EU’s share in Uzbekistan’s total exports increased from 3.8% to 6.3% over the same period. This growth was driven by Uzbekistan’s accession to the GSP+ preferential trade system, granting duty-free access to the EU market across roughly 6,200 tariff lines. The share of Uzbekistan’s exports benefiting from GSP+ reached 59%, with a preference utilization rate of 84%, indicating efficient use of trade benefits.
In 2024, Uzbekistan’s exports to the EU were dominated by chemical products (52.1%), as well as textiles, ferrous and non-ferrous metals, minerals, and food products. Among EU members, France accounted for 47.2% of exports, Lithuania for 10%, and Latvia for 6.9%.
Uzbekistan’s imports from the EU significantly exceeded exports – a reflection of the ongoing technological modernization of the national economy. Around 16% of Uzbekistan’s total imports of machinery, equipment, and transport vehicles come from EU countries.
Investment cooperation is also expanding rapidly. In 2024, foreign investments and loans from EU countries and their financial institutions increased by 77%, reaching $4.1 billion (compared to $2.3 billion in 2023). The most active investors were Germany ($1.37 billion), the Netherlands ($1.05 billion), Cyprus ($858.9 million), the Czech Republic ($137.8 million), Italy ($99.8 million), and Sweden ($97.5 million). Today, around 1,000 enterprises with EU capital operate in Uzbekistan, with a total project portfolio of €30 billion.
A special role in recent years belongs to the EBRD, of which Uzbekistan has become one of the largest beneficiaries. The Bank’s total investments in Uzbekistan’s economy exceeded €5 billion, including around €1 billion in 2024, primarily directed toward the private sector.
Reforms in Uzbekistan have become the key driver for unlocking the significant potential of trade and economic cooperation with the European Union.
Uzbekistan–Belgium
The upcoming visit will also focus on strengthening relations between Uzbekistan and Belgium. Diplomatic relations were established following the opening of the Embassy of Uzbekistan in Brussels in 1993. In 1996, the two countries signed an Agreement on avoidance of double taxation, and in 1998 – an Agreement on mutual protection and promotion of investments, which provide legal guarantees for investors in both states.
Business contacts have intensified in parallel with Uzbekistan’s reform agenda. The visits of 2019 and 2022 set the tone for cooperation in infrastructure, energy, and the digital economy. More important than the current trade volumes has been the recognition and support of Uzbekistan’s reforms by EU partners, laying the foundation for long-term engagement.
In 2024, bilateral trade amounted to $62.3 million, including $7.3 million in Uzbek exports and $55 million in imports. Investment cooperation is gaining momentum: several dozen companies with Belgian capital now operate in Uzbekistan, including wholly owned enterprises. New technologies are being localized, for example, Jaga Climate Designers is participating in a joint venture for heating and ventilation systems, and Picanol Group is localizing the assembly of high-tech textile machinery. Belgian brands Belcolade and Prefamac are exploring opportunities to launch chocolate production with subsequent localization.
Despite modest trade volumes, there is significant potential for expanding cooperation in several areas. Given Belgium’s leading role in pharmaceuticals and biomedical research and Uzbekistan’s growing pharmaceutical market, joint ventures or industrial clusters could be developed in this sector, involving companies such as UCB and Janssen Pharmaceutica.
There is also strong potential for joint fruit and vegetable processing projects in Uzbekistan, targeting exports to the EU via Belgian logistics hubs such as the Port of Antwerp and wholesale markets. Potential partners include Greenyard and Puratos. Direct seasonal exports of fresh fruits (e.g., grapes in autumn and winter), as well as dried vegetables, spices, and organic products, could also be expanded. In light industry, there is room to increase exports of ready-made knitwear and home textiles, provided European quality and safety standards are met. The market potential is evident – Belgium imported about $7.9 billion worth of clothing in 2024.
The main challenges remain logistics and standards. Belgium functions as a major EU maritime hub centered around Antwerp, while direct routes from Uzbekistan are still limited. The near-term priority should be pilot supply chains ensuring quality and traceability, the development of cold logistics, certification under EU technical and sanitary regulations, the use of Benelux consolidation hubs, and trade finance tools for SMEs. With the gradual development of new overland routes along the Middle Corridor, Uzbekistan will gain a stronger foothold in high value-added exports without higher costs or delivery delays.
Conclusion
Uzbekistan is entering a stage of deepened economic cooperation with the European Union. During the ongoing modernization and digital transformation of its economy, European investment, technology, education, and research experience can play a key role. At the same time, Uzbekistan seeks to expand exports of industrial goods as their quality improves.
Uzbekistan is also a rapidly growing market with a young and dynamic population, now reaching 38 million people – an 18% increase since 2017. Every year, around 700,000 economically active individuals enter the labor market, forming a substantial human resource base for the economy, including joint ventures.
As a result of poverty reduction policies, living standards and household incomes have risen significantly. Whereas a third of the population once lived below the poverty line, 7.5 million people have been lifted out of poverty, and the poverty rate declined to 8.9% in 2024, with plans to reduce it further to 6% this year. These policies not only address social challenges but also expand domestic demand, increasing the interest of European businesses in entering Uzbekistan’s market.
The further deepening of Uzbekistan’s economic engagement with the EU and Belgium is an objectively mutually beneficial process – one that will define the success of the upcoming state visit of President Shavkat Mirziyoyev to Belgium.
The agreements expected to be signed will help advance joint projects in sustainable energy and infrastructure, strengthen transport and technological connectivity between Central Asia and Europe, and position Europe as a key partner in Uzbekistan’s long-term growth and modernization trajectory.
Obid Khakimov,
Director of the Center for
Economic Research and Reforms
Economic connectivity between Central and South Asia: a foundation for stability and sustainable development of the macroregion
📅 27.05.2026
- Introduction
Central and South Asia form one of Eurasia’s most significant geographic junctions. Central Asia connects the continent’s east–west and north–south routes, while South Asia contains one of the world’s largest population bases and consumer markets. Taken together, the countries of the two subregions have a population of more than 2 billion people; however, their direct economic interaction remains below its potential level.
The scale of the potential market is confirmed by the figures: in 2024, the population of South Asia was approximately 1.68 billion people, while the region’s combined GDP was about US$4.5 trillion. At the same time, the economy of the five Central Asian countries in 2024 amounted to approximately US$489 billion. However, the level of interregional integration remains low: even within South Asia, intraregional trade is estimated at around 5% of total trade turnover, which is significantly lower than the ASEAN figure[1][2][3].
This is evident in trade statistics: Central Asia’s main trade flows continue to be oriented toward Russia, China, the European Union, Türkiye, and the Middle East, while trade with South Asia occupies a comparatively limited niche.
The underused potential is explained not by a lack of demand, but by structural constraints. Between the two subregions, there are mountain barriers, complex cross-border routes, differing levels of integration into international supply chains, non-uniform customs and technical procedures, as well as the Afghanistan factor, which is simultaneously the shortest connecting link and the most sensitive element of the regional architecture. Therefore, the issue of connectivity has not only commercial but also strategic significance.
The restoration of economic ties between Central and South Asia should not be viewed as a romanticized return to historical routes. In modern conditions, it is a matter of competitiveness, supply-chain security, energy resilience, and diversification of foreign economic directions. For the countries of Central Asia, the southern route opens shorter access to the ports of the Arabian Sea and the Indian Ocean. For the countries of South Asia, it creates an opportunity to gain access to energy resources, food products, industrial goods, and new markets in Eurasia.
Uzbekistan occupies a special place in this logic. It is located in the central part of the region, borders all Central Asian states and Afghanistan, and therefore is capable of forming a link between the internal markets of Central Asia and the southern direction. At the same time, the role of a connector state means more than the transit of goods. It includes the coordination of infrastructure projects, the development of logistics services, the improvement of institutional quality, the creation of an analytical basis for decision-making, and the involvement of the private sector in interregional projects.
- Historical and geographical preconditions for connectivity
The historical connection between Central and South Asia was formed long before the emergence of modern state borders. The cities of Transoxiana, Khorasan, Bactria, and northern India were part of a network of caravan routes and exchanges of artisanal goods, knowledge, religious traditions, and financial practices. Samarkand, Bukhara, Balkh, Merv, Kabul, Peshawar, and Lahore, in different periods, served as trade and cultural hubs linking the Eurasian space.
However, historical connectedness does not automatically translate into economic integration today. Modern supply chains depend on railways, highways, ports, energy networks, digital cargo-tracking systems, insurance, banking settlements, and predictable rules. Where even one of these elements is absent, transit becomes expensive, slow, and risky.
The geography of the region creates both incentives and constraints. On the one hand, the distance from Uzbekistan’s southern borders to northern Afghanistan is relatively short, and the route through Afghanistan is potentially the shortest overland path from Central Asia to Pakistan and onward to the ports of the Indian Ocean. On the other hand, mountain ranges, differences in railway gauge, the limited capacity of border infrastructure, security issues, and insufficient standardization of procedures increase the cost of projects.
Uzbekistan’s geographical role has not only qualitative but also measurable significance: the country is one of only two double-landlocked states in the world and, at the same time, the only state bordering all four other Central Asian countries as well as Afghanistan. In this context, the Mazar-i-Sharif–Kabul–Peshawar railway project, with a length of approximately 573 km, acquires systemic importance, since it could reduce the time and cost of transportation toward Pakistan’s ports by roughly 30%[4].
Therefore, connectivity should be understood more broadly than the physical connection of two points on a map. In the modern economy, it includes four dimensions. The first is infrastructural: roads, railways, terminals, ports, and energy networks. The second is institutional: customs, tariffs, standards, sanitary and phytosanitary rules, permits, and transit guarantees. The third is commercial: demand, purchasing power, contracts, logistics companies, insurance, and banking channels. The fourth is social and humanitarian: education, labor skills, tourism, medical ties, and research cooperation.
This approach helps avoid oversimplification. Even the shortest road will not become a sustainable corridor unless it is supported by a reliable legal environment, competitive tariffs, financial guarantees, and coordination among states.
- Current state of trade and economic cooperation
Trade and economic ties between Central and South Asia are developing, but their scale still does not correspond to the size of the markets. Trade between Central Asian countries and India, Pakistan, Bangladesh, Sri Lanka, and Afghanistan remains relatively modest compared with their trade with China, Russia, the European Union, Türkiye, and countries of the Middle East.
Central Asia supplies, or could potentially expand supplies to South Asia, in such areas as agricultural products, grain, fruit and vegetable products, textiles, fertilizers, energy goods, certain types of metals, and industrial raw materials. South Asia, primarily India and Pakistan, holds competitive positions in pharmaceuticals, medical goods, IT services, equipment, textile products, processed food products, and consumer goods.
In recent years, Uzbekistan has been strengthening the southern direction of its foreign economic policy. Trade ties with India and Pakistan are developing through pharmaceuticals, textiles, food products, services, logistics, and investment projects. Uzbekistan’s foreign trade in the southern direction is already growing, but it still occupies a limited place in the overall structure of foreign trade. The largest trade flows with South Asian countries are with Afghanistan and India. However, the very fact that certain bilateral flows are growing does not solve the main problem: interregional trade remains fragmented. In order to turn it into a sustainable market, it is necessary to reduce transaction costs, ensure the predictability of transit, make standards comparable, and develop business services.
The issue of trade data is especially important. Mutual trade is often assessed using different sources, while the statistics of exporting countries and importing countries may diverge. To develop effective policy, a regularly updated data panel is needed, broken down by corridors, types of cargo, border-crossing times, transportation costs, return loads, the number of permits, and the actual use of preferential regimes. Without such a database, regional initiatives risk remaining merely declaratory.
- Transport and logistics infrastructure as the basis of connectivity
Transport infrastructure is the material foundation for the rapprochement of Central and South Asia. At the same time, it is more accurate to speak not of a single route, but of a portfolio of corridors. Relying on only one route increases the vulnerability of the entire system. A diversified network of routes through Afghanistan, Iran, the Caspian Sea, the Caucasus, and existing Eurasian directions creates redundancy, reduces risks, and strengthens the negotiating position of shippers.
The key project in the southern direction remains the trans-Afghan railway corridor Mazar-i-Sharif–Kabul–Peshawar. Its strategic value lies in its potential to connect Uzbekistan and other Central Asian countries with Pakistan’s ports, including Karachi, Qasim, and Gwadar. If implemented, such a corridor could reduce the distance and delivery time for certain types of cargo. However, the project requires the resolution of several complex issues: financing, security, technical parameters, railway gauge compatibility, the operating model, tariffs, and the distribution of risks among participants.
The Termez–Hairatan hub in Uzbekistan has particular significance. It is the closest entry point from Uzbekistan into Afghanistan and is already used as a logistics, humanitarian, and trade channel. The development of terminals, warehouses, customs capacities, multimodal transport services, and digital cargo-control systems could turn this hub into a stable anchor point for interregional trade.
Alongside the trans-Afghan route, the route through Iran is also important. For India, Central Asia, and Afghanistan, the Chabahar port is of particular significance, as are its links with the International North–South Transport Corridor and the Ashgabat Agreement. This option does not replace the trans-Afghan route, but it increases the resilience of the trade system. Events of recent years have shown that the closure or restriction of individual routes quickly increases the importance of alternative pathways through Iran and the countries of Central Asia.
Road corridors remain a necessary complement to railways. They are especially important for perishable products, small consignments, e-commerce, pharmaceuticals, and high-value-added goods. In this area, the key factors are not only roads, but also border procedures, the permit system for carriers, weight control, insurance, the safety of parking areas, and access to backhaul cargo.
The development of air connectivity plays a separate role. Direct flights between Tashkent, Samarkand, Almaty, Astana, Delhi, Mumbai, Lahore, and other cities do not create mass freight logistics, but they reduce barriers to business travel, tourism, education, medical services, and managerial oversight of investment projects. For modern business, such mobility is not a secondary factor, but a systemic one.
- Energy partnership: from project-based logic to a regional market
Energy is one of the most obvious areas of complementarity between Central and South Asia. The Central Asian countries possess significant resources in natural gas, hydropower, solar power, and wind generation. South Asia, primarily Pakistan, India, Bangladesh, and Afghanistan, faces high energy demand, seasonal consumption peaks, and the need for a more reliable supply structure.
The most advanced interregional project in the electricity sector is CASA-1000. According to World Bank materials, the project is intended to ensure the transmission of up to 1,300 MW of surplus summer electricity from Kyrgyzstan and Tajikistan to Afghanistan and Pakistan. The project also provides for high-voltage transmission infrastructure, including power transmission lines and converter stations. Its significance goes beyond the energy sector: it demonstrates the possibility of contract-based electricity trade between the subregions with the participation of international financial institutions.
In the gas sector, the best-known project is TAPI: Turkmenistan–Afghanistan–Pakistan–India. Its planned logic is straightforward: Turkmen gas is expected to flow through Afghanistan to the energy-deficient markets of South Asia. Published descriptions of the project usually indicate a length of approximately 1,800 km and a designed capacity of up to 33 billion cubic meters of gas per year. However, TAPI remains a complex project with a high dependence on security, financing, long-term contracts, payment guarantees, and political coordination among the participants.
CASA-1000 has not only political but also measurable infrastructural significance: the project cost is estimated at approximately US$1.2 billion, while the designed transmission capacity is 1,300 MW. The Kyrgyz component provides for around 456 km of 500 kV power transmission lines. This makes it possible to view CASA-1000 as the first major example of contract-based interregional electricity trade between Central and South Asia[5][6].
The new energy agenda includes not only the export of fuel and electricity, but also the development of low-carbon solutions. Uzbekistan, Kazakhstan, Kyrgyzstan, and Tajikistan are expanding projects in solar, wind, and hydropower, while also modernizing their grids. In the long term, South Asia could become a market for seasonal electricity and energy services from Central Asia. However, this requires rules for cross-border trade, compatible dispatch mechanisms, commercial guarantees, transparent tariffs, and investment in grid resilience.
Energy cooperation must take into account climate and water-related factors. In Central Asia, hydropower is closely linked to irrigation and water resource management. In South Asia, electricity demand depends on temperature peaks, urbanization, and industrial growth. Therefore, energy projects should be accompanied by mechanisms for climate adaptation, forecasting water availability, improving energy efficiency, and developing energy storage systems.
- Investment cooperation and business ties
Investment cooperation between Central and South Asia is still developing on a case-by-case basis, but it has significant potential. Unlike trade in raw materials, investment requires a higher level of trust, legal certainty, protection of property rights, clear tax regimes, access to foreign-exchange settlements, and high-quality business information.
The most promising areas include pharmaceuticals, medical services, agro-processing, textiles, logistics, warehouse infrastructure, IT services, education, tourism, financial technologies, renewable energy, and the production of components for infrastructure projects. South Asian companies have strong competencies in IT, pharmaceuticals, and services, while Central Asia offers access to raw materials, industrial sites, growing domestic markets, and transit opportunities.
An important task is to move from one-off business contacts to a systematic investment pipeline. This requires project catalogues, clear requirements for investors, standardized public-private partnership models, dispute-resolution mechanisms, insurance against political and commercial risks, and joint workforce training programs.
Small and medium-sized enterprises are of particular importance. Large infrastructure projects create the foundation, but it is small and medium-sized businesses that fill corridors with real goods and services. For them, access to information, affordable logistics services, digital marketplaces, simplified payments, standardized documents, and support in entering a new market are critical.
Development institutions and international financial organizations can play a catalytic role. Their participation reduces risks, improves the quality of project preparation, and disciplines the participants. However, external financing does not replace national reforms. Without clear rules, transparent statistics, and effective courts, even concessional loans will not create a sustainable flow of investment.
- The strategic role of Uzbekistan as a connector state
Uzbekistan possesses a unique set of preconditions for playing the role of a connector state. It is located at the center of Central Asia, borders all the countries of the region as well as Afghanistan, and is also a major demographic and industrial market. For a country without access to the sea, the development of external corridors is not an optional task, but a condition for long-term competitiveness.
Uzbekistan’s role is not limited to transit. A transit country earns revenue from the movement of goods, but a connector state shapes rules, services, trust, and the institutional environment. This means developing multimodal hubs, creating logistics centers, digitalizing customs procedures, expanding railway and road links, training personnel, attracting banks and insurance organizations, and providing analytical support for projects.
The southern direction strengthens Uzbekistan’s foreign economic diversification. It complements the country’s already existing links in the northern, eastern, and western directions. At the same time, the diversification of routes reduces dependence on individual markets and transit pathways, which is especially important amid instability in global trade, changes in tariff policy, and geopolitical restrictions.
Termez occupies a special place in this strategy. It can serve as a border logistics center, a platform for trade with Afghanistan, a hub of humanitarian and commercial infrastructure, and a symbolic space for discussing connectivity between Central and South Asia. To turn this role into a sustainable result, investment is needed in terminals, railway approaches, warehouse capacity, services for carriers, and a system for analyzing cargo flows.
Uzbekistan’s strength also lies in its ability to put forward multilateral initiatives. Interregional connectivity cannot be implemented through bilateral agreements alone. It requires the alignment of interests among the countries of Central Asia, the countries of South Asia, Afghanistan, international financial institutions, business, and the expert community. In this sphere, Uzbekistan can act as a coordinator of the agenda and a provider of analytical solutions.
- Key barriers and ways to overcome them
The first barrier is incomplete infrastructure. Many corridors exist in the form of project concepts or partially functioning routes. To transform them into commercially sustainable directions, technical and economic feasibility studies, agreed tariffs, clear sources of financing, unified operational models, and transparent risk allocation are required.
The second barrier is security and the predictability of transit. For business, what matters is not only the length of the route, but also the likelihood of delays, losses, border closures, changes in rules, and additional payments. Therefore, transport policy should include insurance mechanisms, security standards, corridor monitoring, crisis protocols, and regular information exchange among government agencies.
The third barrier is administrative fragmentation. Different documents, uncoordinated customs procedures, weak advance declaration, the absence of mutual recognition of certain certificates, and limited digital interoperability increase the cost of trade. The solution lies in the transition to electronic transport documents, the expansion of the single-window principle, the introduction of risk-based control, and the coordination of technical standards.
The scale of the financial challenge can be assessed through the example of CAREC: in 2021–2024, transport investment under the program amounted to US$8.61 billion, with a significant share of financing provided by international partners. This shows that infrastructure corridors require not only a political decision, but also a sustainable financial architecture[7][8].
Administrative barriers have a measurable expression. According to CAREC monitoring, in 2022, the average border-crossing time on road corridors was 9.9 hours, while on railway corridors it was 40.6 hours. This confirms that the digitalization of documents, advance declaration, and risk-based control can produce an effect even without the immediate construction of new arterial routes.
The fourth barrier is financial constraints. Infrastructure projects require large capital investments and have long payback periods. A combination of budget funds, loans from international financial organizations, public-private partnerships, guarantees, project financing, and blended-finance mechanisms is needed. At the same time, each project must undergo an assessment of commercial viability, not only political attractiveness.
The fifth barrier is the lack of market information. Companies often do not know potential partners, market requirements, logistics tariffs, certification rules, or available financial instruments. This barrier can be reduced through digital trade platforms, business missions, sectoral catalogues, regular exhibitions, analytical reviews, and consulting centers under chambers of commerce and industry.
The sixth barrier is climate and resource-related risks. Mountainous areas, droughts, floods, changes in glacial runoff, and extreme weather events affect roads, energy, and agriculture. New corridors should be designed with climate resilience in mind, while energy projects should take into account the water balance and the seasonality of demand.
Practical priorities through 2030
|
Area |
Short-Term Focus |
Medium-Term Result |
|
Transport |
Modernization of border terminals, digital cargo tracking and recordkeeping, corridor statistics |
Reduction in delivery time and cost, increased reliability of routes |
|
Trade |
Electronic documents, advance declaration, work on harmonizing standards |
A more predictable regime for exporters and carriers |
|
Energy |
Contractual models, grid investments, consideration of seasonality |
Regional electricity trade and diversification of supplies |
|
Investment |
Project catalogues, guarantee instruments, support for SMEs |
Expansion of private-sector participation and industrial cooperation |
|
Institutions |
Project registry of the Termez Dialogue and annual monitoring |
Transition from declarations to measurable results |
- The Termez Dialogue as an institutional foundation for cooperation
The Termez Dialogue on Connectivity between Central and South Asia can become an important institutional platform for coordinating the interregional agenda. In 2025, the first dialogue was held in Termez, dedicated to the formation of a shared space of peace, friendship, and prosperity. The very choice of Termez emphasizes the city’s practical role as Uzbekistan’s southern hub and as a symbolic point of connection with Afghanistan and South Asia.
The effectiveness of such a format will depend on whether it can move from general statements to the management of a project-based agenda. For this purpose, it would be advisable to structure the dialogue around four permanent tracks: transport and logistics, trade and standards, energy and climate, and investment and human capital. Each track should have a project map, progress indicators, responsible participants, and a mechanism for annual updates.
The participation of business is of particular importance. States can sign framework documents, but real demand for corridors is generated by exporters, importers, carriers, banks, insurance companies, terminal operators, and manufacturing enterprises. Therefore, within the framework of the Termez Dialogue, business sessions, B2B platforms, sectoral presentations, and discussions of specific barriers faced by companies are necessary.
The expert track should serve as an evidence base. It can prepare an annual report on the state of connectivity between Central and South Asia, a corridor-readiness index, monitoring of transportation time and costs, a review of regulatory barriers, analysis of investment projects, and recommendations for governments. In this area, Uzbekistan’s analytical institutions can play a leading role.
The Termez Dialogue is also important as an instrument for involving Afghanistan in economic processes on a pragmatic basis. This is not a matter of political legitimization, but of reducing economic isolation, developing transit procedures, supporting sustainable livelihoods, and creating incentives for stability. This logic corresponds to the interests of all participants, since Afghanistan’s economic predictability directly affects the cost and security of interregional routes.
- Connectivity and the Sustainable Development Goals
Economic connectivity between Central and South Asia is directly linked to the UN Sustainable Development Goals. The development of energy networks supports SDG 7, the expansion of trade and employment corresponds to SDG 8, the construction of resilient infrastructure is linked to SDG 9, the reduction of spatial isolation contributes to SDG 10, climate resilience relates to SDG 13, and regional coordination and partnerships correspond to SDG 16 and SDG 17.
However, the link with the SDGs does not arise automatically. Infrastructure can promote development, but it can also deepen inequality if benefits accrue only to major actors while local communities bear the costs. Therefore, projects should include environmental assessment, social safeguards, consultations with the population, management of land-related issues, occupational safety measures, and transparent compensation mechanisms.
Special attention should be paid to women, youth, and small enterprises. New corridors create demand for services in logistics, trade, catering, repair, digital support, education, and tourism. If access to these opportunities is opened to local entrepreneurs, infrastructure will become a source of inclusive growth, not merely transit rent.
Climate risk is already becoming an economic factor. According to World Bank estimates, by 2030, nearly 90% of South Asia’s population may be exposed to intense heat, while more than one fifth of the population may face the risk of severe flooding. For Central Asia, the key constraint is water: in Uzbekistan, the volume of water withdrawal significantly exceeds internal renewable resources, and the current water deficit may increase to 7 billion m³ by 2030 and to 15 billion m³ by 2050[9][10][11].
The climate dimension of connectivity is becoming increasingly important. South Asia and Central Asia are exposed to the risks of extreme weather events, glacier melt, droughts, floods, and tensions around water. Therefore, new roads, railways, power transmission lines, and logistics centers should be designed with long-term climate scenarios in mind. For the energy sector, this means combining electricity trade, energy efficiency, renewable sources, and grid resilience.
From the standpoint of sustainable development, the most promising model is not one of raw-material transit, but one of value-added creation. This implies agro-processing, industrial cooperation, service chains, digital trade, the localization of selected industries, and workforce training. In this case, connectivity is transformed from the movement of goods into a mechanism of structural modernization.
- Conclusion
Economic connectivity between Central and South Asia is one of the key conditions for the sustainable development of the macroregion. It is capable of expanding sales markets, reducing transport isolation, strengthening energy security, supporting employment, and creating new incentives for regional stability. At the same time, the expected effect depends not on a single project, but on a coordinated package of measures.
The main practical conclusion is the need for a portfolio approach. The trans-Afghan railway, the route through Iran, road corridors, air connectivity, the CASA-1000 and TAPI energy projects, trade digitalization, logistics hubs, and investment platforms should be viewed as mutually complementary elements. Each of them has different implementation timelines, risks, and economic logic; therefore, the regional strategy should ensure redundancy and flexibility.
Uzbekistan has objective advantages for the role of a connector state. Its geography, demographic potential, industrial base, southern hub in Termez, and active foreign economic agenda make it possible to bring together the interests of Central and South Asia.
The Termez Dialogue can become a platform where political will is translated into project-level discipline. For this to happen, it should generate not only declarations, but also a list of projects, indicators, road maps, evaluation mechanisms, and permanent channels of interaction among business, experts, and government agencies.
In the long term, connectivity between Central and South Asia should be oriented not only toward increasing trade volumes, but also toward improving the quality of development. A sustainable macroregion will take shape where infrastructure is connected with institutions, energy with climate responsibility, trade with industrial cooperation, and diplomatic initiatives with evidence-based analysis and practical results.
Muhammad Babadjanov,
Head of Department
at The Institute for Macroeconomic and Regional Studies
under the Cabinet of Ministers of the Republic of Uzbekistan
[1] https://www.worldbank.org/en/programs/south-asia-regional-integration/trade
[2] https://data.worldbank.org/?locations=TJ-UZ-KZ-TM-KG
[3] https://data.worldbank.org/country/south-asia
[4] https://uzembassy.kz/en/article/the-mazar-i-sharif-kabul-peshawar-railway-will-open-up-broad-prospects-for-international-trade
[5] https://www.worldbank.org/en/country/afghanistan/brief/updated-q-a-on-casa-1000-resumption-in-afghanistan
[6] https://www.worldbank.org/en/news/press-release/2023/11/01/additional-financing-for-casa-1000-project-for-the-kyrgyz-republic
[7] https://www.carecprogram.org/uploads/03-CAREC-Transport-Strategy-2030-Midterm-Review-Draft-Report.pdf
[8] https://cpmm.carecprogram.org/2022-report/key-results/
[9] https://www.worldbank.org/en/news/press-release/2025/06/03/climate-resilience-in-south-asia-will-be-private-sector-led
[10] https://data.worldbank.org/country/uzbekistan
[11] https://www.adb.org/news/features/numbers-climate-change-central-asia
Uzbekistan promotes initiatives in Central Asia that unlock new opportunities for cooperation
📅 14.10.2026
Today, the Consultative Meetings of the Heads of State of Central Asia provide the region’s leaders with a regular platform to align their positions on issues that shape the future of Central Asia as a whole. Over the course of eight summits, direct dialogue has evolved into sustained engagement at the level of national coordinators, relevant ministries and agencies, regions, and business communities. From an economic perspective, it is particularly important that trade, industry, transport, and investment are being addressed with due consideration for the interdependence of national development plans.
Central Asia has arrived at its current model of cooperation within a relatively short period of time. In 2017, President Shavkat Mirziyoyev proposed holding regular meetings of the region’s leaders, and the first such meeting took place in Astana in March 2018. The format was built around direct dialogue, allowing the states themselves to define the range of common issues and coordinate their positions in areas where results depend on the actions of neighboring countries. At the same time, the format has retained its fundamentally consultative nature, based on the independence of its participants.
As the scope of cooperation expanded, the necessary mechanisms were gradually established. In 2021, establishment of a Business Council was proposed. In 2022, the Treaty on Friendship, Good-Neighbourliness and Cooperation for the Development of Central Asia in the 21st Century was signed. The Council of National Coordinators was established in 2023, and a year later the Central Asia 2040 Concept for the Development of Regional Cooperation was adopted. In this way, political dialogue acquired an institutional and legal framework between summits while preserving the flexibility of the original format.
Uzbekistan’s chairmanship in 2025 significantly strengthened sectoral cooperation. More than 20 major sectoral and interregional events were held, including the Interregional Cooperation Forum at the level of deputy prime ministers. Ahead of the Seventh Consultative Meeting in Tashkent, the first meeting of the Council of Ministers of Trade and Investment of the Central Asian countries and Azerbaijan was held. Discussions focused on practical objectives: increasing mutual trade to USD 20 billion, establishing production facilities under the “Made in Central Asia” brand, and attracting international financial institutions to infrastructure and industrial projects.
The current scale of economic ties makes it possible to pursue more ambitious objectives. By the end of 2025, Uzbekistan’s trade turnover with the Central Asian countries had reached USD 8.3 billion, an increase of 15.2 percent. In the same year, the volume of direct investment and loans attracted from countries in the region amounted to USD 1.3 billion. Growing trade and investment activity is creating a foundation for deeper industrial cooperation and the development of production chains among enterprises across the region.
This is the underlying rationale of “Made in Central Asia.” Enterprises from several countries can participate in the creation of a final product by distributing individual stages of production among themselves. For Uzbek businesses, such a model expands the pool of potential customers and enables production to be planned in response to demand beyond the domestic market. A practical foundation is already taking shape: an Action Plan for the Development of Industrial Cooperation for 2025–2027 has been approved, bilateral investment funds have been established, cross-border trade zones and industrial cooperation centers are being developed, and joint sectoral projects are being implemented.
The economics of production chains is directly dependent on logistics. The China–Kyrgyzstan–Uzbekistan railway, as well as the Trans-Afghan and Trans-Caspian routes, involve different groups of participating countries.
The consultative platform provides an opportunity to coordinate countries’ infrastructure plans, border crossing operations, and logistics hubs in advance. In 2025, Uzbekistan proposed establishing an Infrastructure Development Council at the level of deputy prime ministers in order to place such coordination on a permanent footing.
A more favorable business environment is also being shaped through decisions taken in bilateral and trilateral formats. Since 2023, citizens of Uzbekistan and Kyrgyzstan have been able to cross the shared border using ID cards. In 2025, Uzbekistan, Kyrgyzstan, and Tajikistan signed a treaty on the junction point of their state borders. These measures facilitate travel, business contacts, and cross-border trade.
Azerbaijan’s accession as a full-fledged participant in November 2025 expanded the permanent dialogue toward the South Caucasus and brought into the format a country located along the continuation of the Trans-Caspian routes. This makes it possible to address trade, transport, energy, and investment issues within a broader economic geography.
At the same time, the planning horizon is expanding. The Central Asia 2040 Concept established long-term priorities, while at the Tashkent summit Uzbekistan proposed developing a Comprehensive Regional Program for Trade and Economic Cooperation through 2035, adopting a Declaration on a Common Investment Space, and introducing a joint program for the development of e-commerce. For businesses, these initiatives create a more predictable horizon for planning investments, supply chains, and entry into neighboring markets.
Uzbekistan’s proposal to move toward a strategic “Central Asian Community” format also fits within this longer-term perspective, with the aim of strengthening continuity in the implementation of long-term infrastructure, industrial, and investment initiatives.
Following the conclusion of Uzbekistan’s chairmanship, the focus continued to shift toward new forms of economic connectivity. At the informal meeting of the heads of state of Central Asia and Azerbaijan in July 2026, Uzbekistan proposed substantive work on integrated industrial and technological value chains, shared digital services, and investment platforms.
The mechanisms developed in recent years make it possible to connect suppliers across several countries, establish production facilities serving broader markets, attract capital to projects of regional scale, and incorporate logistics considerations from the earliest stages of investment planning. The established channels of cooperation facilitate the transition from strategic priorities to concrete projects while preserving each state’s independence in decision-making. Translating high-level agreements into programs and measurable results is what defines the substance of the next stage.
For Uzbekistan, this represents a qualitatively new scale of regional economic policy. Central Asia is becoming a space where coordinated decisions expand the potential market for national enterprises, connect production capacities, open new routes, and strengthen the foundation for investment. This is precisely where the strategic significance of the platform lies: the countries of the region are themselves shaping the conditions for long-term growth, while Uzbekistan consistently advances initiatives that translate the potential of good-neighborly relations into tangible economic opportunities.
On September 4–6th, Samarkand will host XII Inter-Parliamentary Union Global Conference of Young Parliamentarians
📅 20.08.2026
The XII Inter-Parliamentary Union (IPU) Global Conference of Young Parliamentarians will be held on September 4–6th, 2026, in the city of Samarkand, under the theme “Restoring Human Rights, Justice and Dignity for All in Fragile Times”.
The XII Global Conference is expected to convene approximately 300 delegates representing 183 countries, 15 international organizations and around 50 permanent observers.
Event program includes six thematic sessions, during which the participants will address pressing issues pertaining to the status and rights of youth in the contemporary world. Specifically, particular attention will be devoted to protecting the rights of young people amid conflicts and digital transformation, expanding their political rights and opportunities, ensuring economic rights and youth employment, as well as preventing violence against women and youth.
Conference agenda envisages innovative and interactive working formats, including breakout discussions, training sessions, and dialogue forums. This approach is designed not only to facilitate a substantive exchange of views but also to foster the development of professional contacts among young parliamentarians from different countries.
An essential component of the conference will be the convening of the Third Global Forum on Inter-Parliamentary Cooperation for Achieving the Sustainable Development Goals. The participants will review the role of parliaments and inter-parliamentary interaction in advancing the Sustainable Development Goals, alongside opportunities to enhance youth contributions toward implementing the global agenda.
Following the conference, the adoption of a final document is expected, which will contain recommendations and joint approaches of young parliamentarians on the core issues of the event's agenda.
Official working sessions of the conference will take place on September 4–5th. The third day, September 6th, will be dedicated to a cultural program organized by the parliament of the host country.
Annual IPU Global Conference of Young Parliamentarians was established in 2014. The conference mechanism is aimed at enhancing the role of young parliamentarians and expanding youth participation in parliamentary activities, formulating recommendations that reflect youth perspectives on the IPU’s activities and agenda, as well as broadening opportunities for networking, strengthening solidarity and developing the capacity of young people.
IPU initiative to support youth participation in political life dates back to 2010, when the resolution “Youth participation in the democratic process” was adopted at the 122nd Assembly of the organization in Bangkok. The document underscored the necessity of full and active participation of youth and youth organizations in democratic processes at local, national, regional and international levels.
In furtherance of this initiative, IPU established the Forum of Young Parliamentarians in 2013 - an official, permanent body aimed at quantitatively and qualitatively enhancing youth participation within parliaments and the activities of the IPU.
To date, eleven Global Conferences of Young Parliamentarians have been convened, addressing a broad spectrum of pressing issues, ranging from youth participation in politics and democracy to digital transformation, climate change, education, employment and gender equality.
Dunyo IA
Samarkand
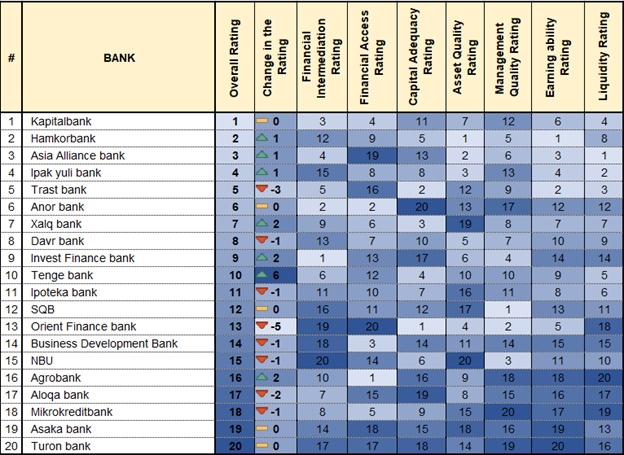
CERR Updates Bank Ranking for Q1 2026
📅 17.04.2026Following the results of Q1 2026, the ranking of large banks underwent notable changes. While the leading group remained intact, positions within the segment were reshuffled. In the small-bank category, movements were also significant, pointing to continued realignment and stronger competition across the sector.
The Center for Economic Research and Reforms presented the updated Bank Ranking based on the results of the Banking Activity Index for Q1 2026.
The study covers 34 commercial banks of the republic, including 20 classified as large financial institutions by scale and branch network, while the remaining 14 were categorized as small banks.
The methodology is based on the analysis of 27 indicators benchmarked against national averages and international standards, including the requirements of the Basel Committee. The ranking serves as an important tool for enhancing transparency and strengthening confidence in the financial system. This approach is consistent with international practice and is widely used by leading financial institutions.
Financial Results for Q1 2026
During the reporting period, total assets of the banking sector amounted to 932.3 tn sums ($76.3 bn), while liabilities reached 793.9 tn sums ($64.9 bn). Lending increased by 14%, while deposits grew by 32%. The aggregate capital of the banking system was fully denominated in the national currency. Net profit reached 3.1 tn sums ($254 mn), which is 36.3% higher than a year earlier.
During the period under review, the share of non-performing loans declined to 3.3%, compared with 4.5% a year earlier, indicating improved portfolio quality. At the same time, in several banks the ratio remains above the sector average. Capital adequacy indicators exceed minimum regulatory requirements by more than 1.4 times, confirming the resilience of the banking sector.
Large Banks Activity Ranking for Q1 2026
The results of Q1 2026 show that despite the relative stability at the top of the ranking, both categories of banks recorded notable positional changes.
In the large-bank segment, performance was mixed. Out of 20 banks, 7 improved their positions, 8 declined, and 5 retained their previous places. This reflects a high level of competition and the ongoing redistribution of market positions.
The most notable progress was demonstrated by Tenge Bank, which moved up by 6 positions. Three more banks — Agrobank, Invest Finance Bank, and Xalq Bank — advanced by 2 positions each. Positive momentum was also recorded by Ipak Yuli Bank, Asia Alliance Bank, and Hamkorbank, all of which improved their standing in the overall ranking.
At the same time, several large banks recorded lower activity levels. The most significant decline was observed at Orient Finans Bank and Trast Bank, which fell by 5 and 3 positions respectively.
Changes Across Key Indicators
Financial Intermediation. The leading positions were taken by Invest Finance Bank, Anor Bank and Kapitalbank. In this ranking, Davr Bank and Hamkorbank fell by 4 positions, while Ipoteka Bank declined by 1 position.
Financial Accessibility. The leaders were Agrobank, Anor Bank and BRB. Under this indicator, declines were mainly observed among leading banks: Kapitalbank (-3 positions), Hamkorbank (-7), Asia Alliance Bank (-1), Ipak Yuli Bank (-5), and Trast Bank (-6). The strongest improvement in this ranking was recorded by Tenge Bank (+8), Xalq Bank, Davr Bank (+5), and Agrobank (+4).
Capital Adequacy. The top positions were occupied by Orient Finance Bank, Trast Bank and Halk Bank. At the same time, Agrobank dropped by 4 positions, while Aloqa Bank declined by 2 positions.
Asset Quality. The leaders were Hamkorbank, Asia Alliance Bank and Ipak Yuli Bank. Turonbank fell by 5 positions, while Asakabank, Mikrokreditbank, SQB, Trast Bank and Anor Bank each declined by 2 positions.
Management Efficiency. The highest positions were held by SQB, Orient Finance Bank and NBU. At the same time, Asaka Bank dropped by 5 positions, while BRB declined by 4 positions.
Profitability. The leaders were Hamkorbank, Trast Bank and Asia Alliance Bank. Turon Bank, after falling by 3 positions, ranked last. In this ranking, Kapitalbank, Asia Alliance Bank, Anor Bank and Davr Bank declined by 2 positions, while Ipoteka Bank and Mikrokreditbank fell by 1 position.
Liquidity. The leaders were Asia Alliance Bank, Ipak Yuli Bank and Trast Bank. At the same time, Mikrokreditbank, Ipoteka Bank, Anor Bank and SQB each declined by 1 position.
Small Banks Activity Ranking for Q1 2026
The small-bank group remained relatively stable, with leading institutions retaining their positions. The main changes in this category were concentrated in the middle segment, where several banks improved their standing due to stronger financial intermediation and higher profitability.
Within this group, 8 out of 14 financial institutions improved their rankings. The most notable gains were recorded by AVO Bank and Apex Bank, both rising by 3 positions. TBC became the leader of the ranking.
At the same time, 5 banks moved down, with the sharpest decline recorded by Octobank, which lost 6 positions. Saderat Bank, Garant Bank, and Ziraat Bank each rose by 2 positions. The ranking was rounded out by Open Bank and Uzum Bank, both up by 1 position.
Jafar Khidirov, CERR
CERR Banking and Financial Sector Research Sector
Tel: (78) 150 02 02 (441)
CERR Public Relations and Media Sector
Tel: (78) 150 02 02 (417)
The dynamics of Uzbek-Turkish relations reflect pragmatism, mutual trust and a focus on concrete results.
📅 30.01.2026
The First Deputy Director of the Institute for Strategic and Regional Studies under the President of the Republic of Uzbekistan Akramjon Nematov shared this assessment, commenting on the results of President of the Republic of Uzbekistan Shavkat Mirziyoyev's visit to Turkiye.
According to him, the official visit of the Uzbek leader to the Republic of Turkiye, which concluded on January 29, 2026, should be viewed not only as another event on the bilateral political calendar, but above all as an important milestone in the institutional strengthening of Uzbek-Turkish relations. Its results convincingly confirmed that the interaction between Tashkent and Ankara, which was largely fragmented just a few years ago, has reached a qualitatively new level – the level of a comprehensive strategic partnership based on pragmatism and mutual benefit.
The personal role of President Shavkat Mirziyoyev in shaping this new quality of relations deserves special mention. His proactive policies and strategic approach have enabled bilateral cooperation to reach a systemic level, where pragmatism is combined with a long-term focus on sustainable development. Thanks to the President's initiative, visits and cooperation programs have become regular and institutionalized, and the agreements reached have begun to be implemented with clear planning and measurable results, strengthening trust between the countries and creating a reliable platform for economic, humanitarian, and technological ties.
Thus, the current visit's program, which included talks in narrow and expanded formats, as well as the fourth meeting of the High-Level Strategic Cooperation Council, demonstrated a high level of political trust and the maturity of the bilateral dialogue. While such meetings were previously held sporadically, today the Strategic Cooperation Council functions on a regular basis, ensuring the continuity of decisions and overseeing their implementation. Symbolically, the key events took place on the eve of the holy month of Ramadan and the 30th anniversary of the Treaty of Eternal Friendship and Cooperation, underscoring the value-based and historical foundation of the partnership.
Of fundamental importance is the fact that Uzbek-Turkish cooperation is currently characterized by constructive and pragmatic mutual approaches, and is being built as an open partnership model focused on ensuring shared security and sustainable development. This is reflected in the finalization of the "4+4" format, which brings together coordination across foreign policy, defense, and law enforcement agencies. Unlike previous consultation mechanisms, this format is practical in nature and allows for a systemic response to cyber threats, cross-border crime, and other unconventional challenges.
The economic dimension of the partnership demonstrates sustained positive momentum and a high degree of complementarity. In recent years, mutual trade has more than doubled, reaching $3 billion by the end of 2025, compared to just $1.5 billion at the beginning of the decade. The goal set by the heads of state to increase trade turnover to $5 billion is supported not by mere declarations, but by a real investment portfolio of approximately $9 billion. The number of enterprises with Turkish capital has also increased significantly: while there were previously hundreds, today over 2,100 such companies operate in Uzbekistan, demonstrating growing business confidence and the formation of a solid material foundation for the strategic partnership. The need for further advancement of projects in industry, agriculture, social protection, and other priority areas was emphasized, including by expanding the list of goods covered by the Preferential Trade Agreement.
In preparation for the visit, new priority areas of industrial cooperation were identified, which will be implemented under a separate program. Compared to previous stages of cooperation, which focused primarily on trade and construction, the current emphasis is on joint production, localization, and export-oriented industries. Particular attention is paid to developing cooperation in tourism, theater festivals and cultural weeks, joint production of historical films, and the restoration of cultural heritage sites, reflecting the expanding humanitarian component of the partnership.
It is particularly noteworthy that the agreements reached are directly aimed at addressing the structural challenges of Uzbekistan's national development. The development of the Middle Corridor and the cooperation in transport and transit enshrined in the corresponding protocol are aimed at overcoming the country's geographic isolation and diversifying external logistics routes. Compared to traditional routes, these solutions reduce delivery times and increase the resilience of supply chains. Agreements on industrial cooperation, the management of special economic zones, and the creation of joint clusters contribute to reducing the economy's reliance on raw materials and fostering high-value-added production. The transfer of technological competencies, including nuclear safety and digitalization, should be viewed as an element of sovereign modernization, not technological dependence.
A fundamentally new stage has been the expansion of cooperation to the regional level. The intention to organize visits by delegations from all regions of Uzbekistan to Turkiye reflects the transition from a centralized model of interaction to a more flexible, decentralized partnership architecture. While interregional contacts were previously limited, the Action Plan for 2026–2027 envisages the formation of sustainable partnerships between the regions of the two countries, the launch of joint projects, and the development of a portfolio of local initiatives. Significant potential for implementing advanced Turkish practices in agriculture, horticulture, healthcare, and medical tourism has also been noted.
The military-technical cooperation sector deserves special attention. Compared to previous years, when interaction was limited to consultations, the signed agreements provide for deeper cooperation in military medicine, personnel training, and the implementation of surveillance systems and unmanned aerial vehicles. This cooperation is exclusively defensive in nature and is aimed at enhancing the professional level and technical capabilities of the Armed Forces of Uzbekistan, which is a rational contribution to strengthening national defense capability.
The humanitarian dimension of the Uzbek-Turkish partnership lends further depth and stability to the relationship. The implementation of the Cultural Cooperation Plan for 2026–2027, the agreement to hold the fourth Rectors' Forum in Bukhara, and joint education projects form a long-term foundation for cooperation. Uzbekistan's participation in the reconstruction of the earthquake-damaged Hatay province, the construction of the "Uzbekistan" residential complex, and a comprehensive school have become clear examples of practical solidarity. The start of construction of an Uzbek school in the Bekirkoy district of Istanbul—Uzbekistan's first educational institution abroad—is also symbolic, reflecting the strategic focus on the humanitarian aspect of cooperation and outreach to the diaspora.
Overall, the visit to Turkiye confirmed that Uzbek-Turkish relations are developing as a pragmatic, dynamic, and responsible partnership. Compared to previous stages of bilateral cooperation, the current format is characterized by greater institutional stability, expanded economic and regional cooperation, and deepened humanitarian ties. The agreements reached create additional tools for overcoming transportation and technological constraints, modernizing the economy, strengthening defense capabilities, and ensuring shared security, forming a solid foundation for further expanding Uzbekistan's international cooperation in a changing global environment.
«Dunyo» IA
Tashkent

-
 Ministry of Foreign Affairs of the Republic of Uzbekistan
-
 Diplomatic Service of the Ministry of Foreign Affairs
-
 State Committee for Tourism Development
-
Ministry of Investments and Foreign Trade of the Republic of Uzbekistan
-
 invest.gov.uz
-
-
-
-
-
-
-

of Uzbekistan in the Republic
of Latvia
When using the information, a link to www.uzembassy.lv
must be provided.
All rights reserved
Address
Address: Riga c., LV-1010. 11-11 Elizabetes Str., Latvia
Phone: 37167322424
Fax: 37167322306
Email: embassy@uzbekistan.lv
Useful links
HomeIssuance of biometric passport for departure abroad
Certificate to return to Uzbekistan
Withdrawal of citizenship
Loss of citizenship